Audited Financial Statements in the UAE: Who Needs Them and By When
Many founders assume a small UAE company will never need audited financial statements, until a bank, a buyer or the Federal Tax Authority (FTA) asks for them. Since the introduction of corporate tax, audit requirements have become more defined, and the answer now depends on a company’s tax status, revenue, jurisdiction and commercial relationships. Settling that position early avoids a rushed audit just before a filing deadline.
What Audited Financial Statements Are
Audited financial statements comprise a company’s balance sheet, income statement, cash flow statement and accompanying notes, examined by an independent licensed auditor who issues an opinion on whether they present a true and fair view. In the UAE, they are generally prepared under International Financial Reporting Standards. The auditor’s opinion may be unqualified, qualified, adverse or a disclaimer. Management accounts are different: they are internal and unverified, and while they support day-to-day decisions, banks, regulators and investors usually want independent assurance. A detailed guide to audited financial statements in the UAE covers the requirements for different company types.
Who Must Be Audited for Corporate Tax
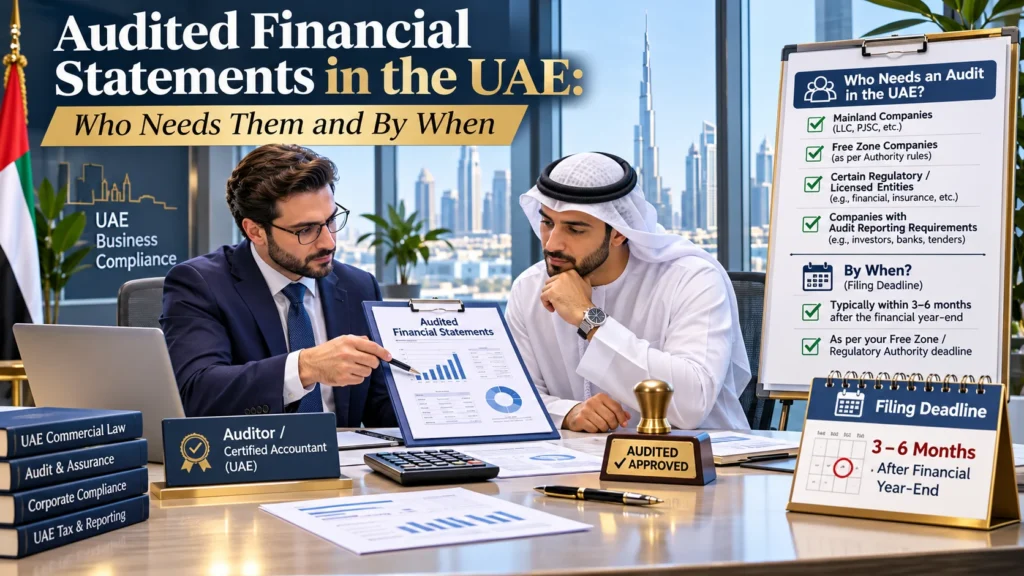
The corporate tax audit rules are set by Ministerial Decision No. 84 of 2025, which applies to tax periods starting on or after 1 January 2025 and replaced Ministerial Decision No. 82 of 2023. It identifies three categories. A taxable person that is not part of a tax group must prepare audited financial statements if its revenue exceeds AED 50 million in the tax period. Every Qualifying Free Zone Person must prepare them regardless of revenue. Every tax group must prepare audited special purpose financial statements, whatever its combined revenue.
The Qualifying Free Zone Person rule has the widest practical impact. Audited statements are a condition of the 0% rate on qualifying income, so a small free zone company relying on that rate cannot treat the AED 50 million threshold as its audit test. A free zone company paying the standard 9% rate with modest revenue, by contrast, may have no corporate tax audit obligation at all.
Other Reasons a Company May Need an Audit
Falling outside the corporate tax categories does not mean a company never needs an audit. Company law, free zone regulations and sector regulators can impose their own requirements, and many free zone authorities can request audited statements as part of their oversight or renewal process. Regulated and public companies follow the rules of their sector regulator, such as the Securities and Commodities Authority.
Commercial pressure is often just as significant. Banks commonly ask for audited accounts when assessing credit facilities, trade finance or periodic reviews, and investors rely on them for valuation. An SME applying for trade finance may be asked for two years of audited statements, which makes a voluntary audit a practical necessity.
Timing the Audit
Audit timing follows the financial year-end and should be planned backwards from the corporate tax return deadline, which falls nine months after the end of the tax period. A company with a 31 December year-end must therefore file by 30 September of the following year, and the audit must be signed off before then. In practice, the books should be closed and reconciled early in the new year, a licensed auditor appointed with scope and fees agreed in writing, and fieldwork completed with ledgers, bank statements, contracts and VAT records ready. Missing supplier invoices or unreconciled balances are among the most common causes of delay.
Costs and Consequences
A missing or late audit can cost a Qualifying Free Zone Person its 0% rate on qualifying income. It can also push the tax return past its deadline and trigger FTA penalties for late filing, which accrue monthly. Beyond tax, a delayed audit can hold up license renewals and stall banking reviews. Audit fees are a recurring annual cost that depends on revenue, transaction volume and bookkeeping quality, and they should be treated as estimates until an auditor confirms them in writing.
Conclusion
Audited financial statements are mandatory for some UAE companies, expected by banks and investors for many others and available on request to many licensing authorities. Checking tax status, revenue and tax group membership against the current rules, then appointing an auditor early, keeps the process manageable. Companies licensed through free zones such as Meydan Free Zone should confirm their Qualifying Free Zone Person position and their authority’s audit requirements well before year-end.