Personal Loan or Loan on a Credit Card? What You Must Know
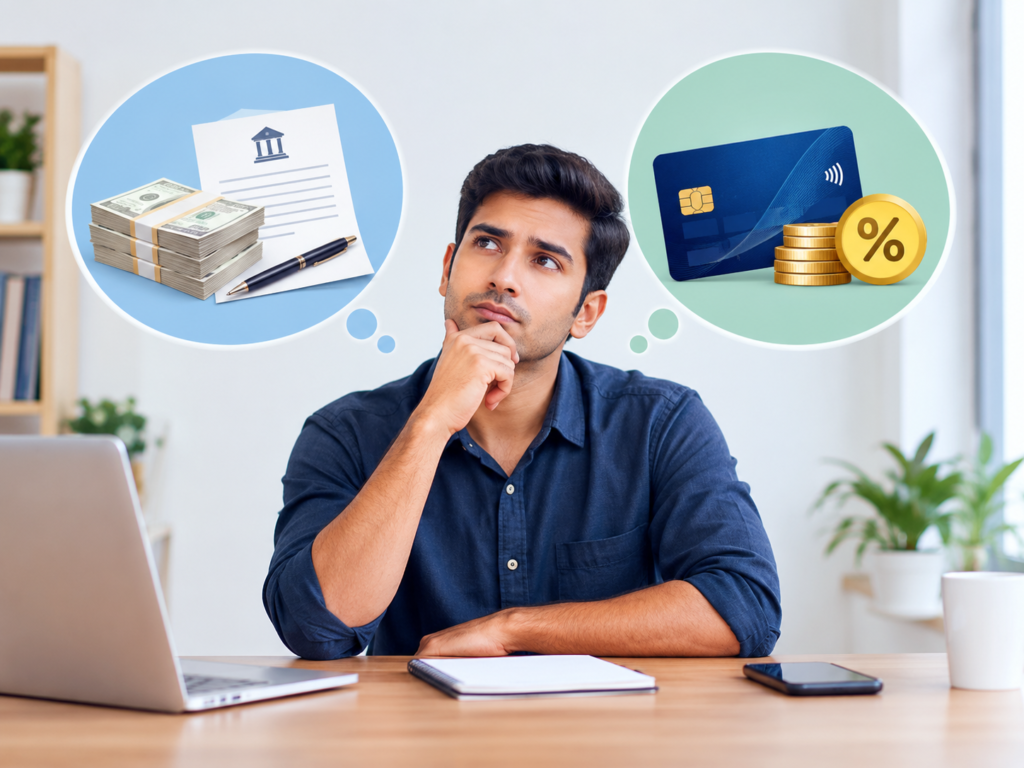
Personal loans and credit card loans are two common options people usually choose when they need money urgently. At first glance, a card loan can be tempting. The money is available quickly, and promotional offers can sometimes advertise low or even 0% interest. A personal loan, on the other hand, usually involves more documentation and a formal repayment schedule. But it usually charges a lower interest rate than a credit card.
What Do You Understand by a Personal Loan in the UAE?
A personal loan is a financing facility offered by banks and financial institutions in the UAE. Through this type of loan, the bank gives you an amount that you repay through scheduled EMIs over an agreed period.
A personal loan may be worth considering when you want a clear repayment structure and need a relatively larger amount. Your EMI is set upfront, making it easier to include in your monthly budget. You also don’t have to use your credit card limit.
However, approval depends on factors such as your income, existing liabilities, credit score, and the lender’s eligibility criteria. As per the law, UAE banks have to check your ability to meet credit obligations and consider existing debt when assessing applications.
What Do You Mean by a Loan on a Credit Card?
A loan on a credit card allows you to borrow against your available card limit, depending on the offer provided by your bank. It may be marketed as a cash loan, quick loan, loan-on-card or similar facility.
This finance option can be convenient if your bank has already made an offer available to you and you need the money relatively quickly. It can also be worth comparing when the bank is running a promotional offer with competitive repayment terms.
While choosing this option, know that it uses a large portion of your credit limit. This can leave you with less available credit for future expenses. If you already have a significant outstanding balance on the card, adding another repayment commitment requires extra consideration.
Look Beyond Interest Rate When Comparing Finance Options
A 0% or low-interest offer can look attractive, but that’s not necessarily the case. While borrowing money, look at these key factors:
- Processing or administration fee
- Total amount payable
- Monthly instalment
- Repayment tenure
- Early settlement charges
- What happens if you miss an instalment
- Whether the facility reduces your available credit limit
For example, two lenders offer AED 20,000. One advertises a lower rate but charges a higher processing fee. The other one, meanwhile, has a slightly higher rate but lower upfront charges. In this case, looking only at the interest rate could give you the wrong impression.
A more useful comparison is how much you will pay from the first instalment to the last. UAE banking regulations require applicable interest rates and charges to be disclosed. Moreover, the Central Bank’s responsible-financing standards require the APR, including interest/profit and relevant fees, to be disclosed.
What About a 0% Credit-Card Loan?
You may have seen this offer frequently, but this is where the hidden terms matter. A promotional 0% offer may mean that no interest is charged during a specific period, but there could still be a processing fee or other applicable charges. The offer may also have specific eligibility and repayment conditions.
So, when you see ‘0% interest rate on credit card loan,’ ask the bank for the total repayment amount, including all applicable fees. If the offer is genuinely interest-free and the fee is reasonable, it may suit for a short-term borrowing need.
Personal Loan or Credit-Card Loan: What Should You Compare?
Instead of asking which financial product — personal loan vs credit card loan — is better, compare the two offers using this checklist:
| Factors | Personal Loan | Credit Card Loan |
| Loan Amount | High amount, depending on the eligibility | Based on available/approved card limit |
| Repayment | Fixed EMI for long term, usually up to 4 years | Usually fixed instalments for a short tenure |
| Processing | Documentation and banks’ approval is required | Quick loan disbursal |
| Interest Rate | Low-interest rate | Typically, higher than personal loan |
| Credit Limit | Separate from card limit | Reduces available card limit |
The Bottom Line
A personal loan may offer a more structured way to borrow. A credit-card loan can give more convenience and, in some cases, attractive promotional terms.
However, don’t judge either option by the headline rate alone.
Before applying for a loan option, compare the total amount payable, monthly EMI, fees, repayment period, and the impact on your existing credit commitments. A few minutes spent comparing the complete numbers can tell you far more than a “low-rate” or “0%” label.